The Lesson Banks Won’t Teach
A Bloomberg financial journalist argues that financial literacy courses blame people for poor financial results when an industry that profits from those results is responsible.
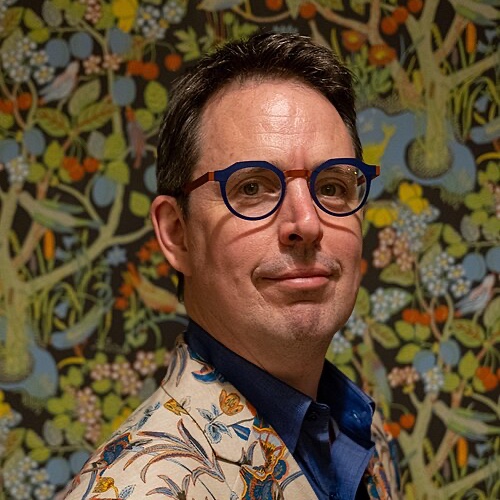
FELIX Salmon is one of the best-known financial journalists in the English-speaking world. Born in Britain and based in New York, he has written about money and markets for Reuters, the online magazine Slate and the news site Axios, where he was chief financial correspondent, before joining Bloomberg as a senior writer in 2025, and he co-hosts the long-running Slate Money podcast.
In a widely read Axios piece he took aim at what he called the "financial literacy industrial complex": the courses, campaigns and corporate-sponsored programmes that promise to fix people's finances by teaching them about money. Many of our readers sit through exactly these lessons at school, so we asked him why the idea is so popular, who benefits from it, and what a more honest approach to money would look like.
The Confluence: Your Axios piece argued that the "financial literacy industrial complex" promises far more than the evidence shows it delivers. Why does the idea remain so politically popular, and who benefits from it persisting?
Salmon: The deep idea behind financial literacy is that it's up to the individual whether they're financially in a good place or not. That's always going to be politically popular, since it allows politicians to effectively blame their constituents, rather than themselves, when those constituents end up in a bad financial place. Who benefits from it? The financial services industry writ large, and also small-government types who don't think the government can or should take responsibility for the people's financial health.
The Confluence: If bad financial outcomes aren't mainly a problem of individual knowledge, where does responsibility actually lie: in how products are designed, how they're regulated, or in the structure of wages and credit? What would a serious policy agenda look like if it started from that premise?
Salmon: All of the above, and more. Finance is deeply embedded in the economy, and you need a complex-systems approach [treating the economy as a web of interacting parts] to even begin to understand what sensible policy responses should be. But certainly the ideas that the financial services industry can self-regulate, and that market forces will generate optimal outcomes, are clearly false.
The Confluence: A lot of financial education is sponsored by banks and other financial firms. How should students think critically about who is teaching them about money, and are there other areas of public life where the same conflict of interest goes unnoticed?
Salmon: One salutary exercise is to look at the share of S&P 500 [a stock-market index of 500 large US companies] profits that goes to financial services. Roughly one in every five dollars of profit made by US corporations each year goes to these middlemen, which is a huge amount.
If the market were remotely efficient, surely most of those profits would be competed away, but in reality JPMorgan alone makes more than $60 billion of profit every 12 months, more than $1 billion every week. All of that money comes from JPMorgan's customers, in one way or another, including anyone with a Chase checking account or credit card. So does it behove these banks to teach their customers how to hold on to that money for themselves? Not really.
The same kind of thing can be seen in other areas where industry preaches individual responsibility: in gambling, or in nutrition (the Global Energy Balance Network, funded by Coca-Cola, pushed "exercise more" over "eat less sugar"), or in energy and climate, where industry loves to focus on individual rather than societal or regulatory attempts to reduce carbon emissions.
The Confluence: Many young people now learn about money through TikTok, crypto communities and trading apps rather than in classrooms. Is that better or worse than what it replaced, and what worries you most about it?
Salmon: A lot of this advice is terrible, but I'm honestly not sure how many young people are following it uncritically. During the meme stock mania of 2021, a lot of younger folks got into highly risky investments, such as meme stocks [shares, like GameStop's, driven up by online hype], crypto and NFTs, and ended up losing a lot of money. It was an expensive lesson, but on some level they knew that what they were doing was risky, they broadly lost money they could afford to lose, and they had fun with their YOLO bets.
I think what worries me most is that when TikTok influencers get replaced by large sports-betting companies with multibillion-dollar valuations like Kalshi, objectively bad advice can become normalised, to the point at which people stop doing something thrillingly transgressive and start just losing money to rentiers [those who profit from owning something others must pay to use].
The Confluence: Beyond financial literacy, which other piece of widely accepted financial wisdom do you think is most overrated, and why has it proved so durable?
Salmon: The idea that homeownership is a great investment that most people should aspire to. Again, there are a lot of vested interests here, including the 65 per cent of the population who already own a home and want demand for their asset to be as high as possible.