The Kwacha Squeeze
A falling kwacha pushes up food and fuel prices in Malawi, and access to credit decides who copes best, a Malawian economist explains.
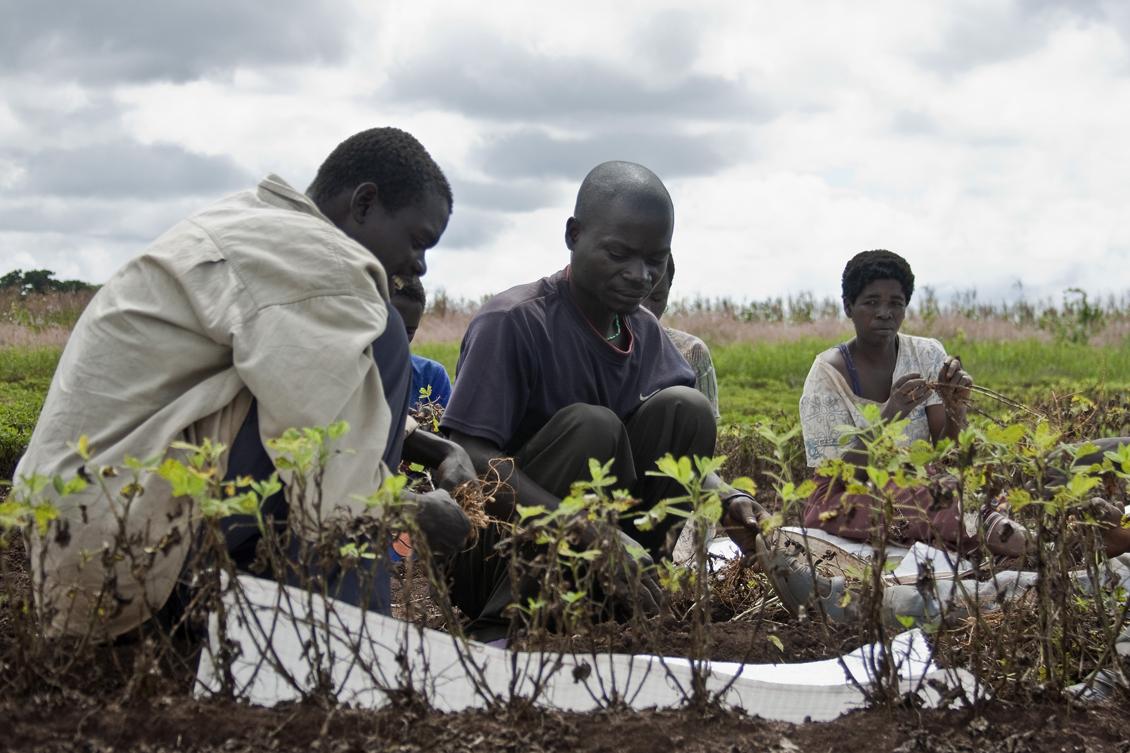
FREDRICK M. Banda is an economist at the Malawi University of Business and Applied Sciences (MUBAS) in Blantyre, where he researches Malawi's exchange rate and money supply, agricultural and financial economics, and what makes firms on the Malawi Stock Exchange profitable. Malawi is one of the poorest countries in the world, and most of its people farm small plots of land, so the questions he studies are not abstract: when the kwacha, Malawi's currency, loses value, families feel it at the market within weeks.
We asked him how that happens, what a pandemic did to the currency, and why a GDP figure can hide more than it shows.
The Confluence: Malawi's currency and its food and fuel prices have all been volatile in the last few years. In simple terms, how does a weaker kwacha end up making food and energy more expensive for ordinary Malawians, and why does that hit harder in an economy like Malawi's than in a more diversified one?
Dr. Banda: Malawi buys much of its fuel, key agricultural inputs such as fertiliser, and some food from abroad. So when the kwacha loses value against the US dollar or other major currencies, Malawian importers need more kwacha to buy the same amount of goods priced in foreign currency. That higher cost gets passed down to wholesalers, retailers and eventually ordinary households.
Food prices rise for three reasons. Fuel and fertiliser are key inputs for farming, so if they become more expensive, farmers' production costs rise. Transporting food also depends on fuel, so higher fuel costs push up the price of maize, rice and other staples. And imported foods, like wheat or cooking oil, directly become more expensive because they are priced in foreign currency.
Energy prices rise for similar reasons: Malawi imports nearly all of its petroleum products, so a weaker kwacha means every litre of petrol or diesel costs more in local currency, and electricity generation also depends partly on imported inputs, so tariffs can rise when the currency weakens.
This hits Malawi harder than a more diversified economy for four reasons. First, high import dependence: Malawi relies heavily on imports for essentials like fuel and fertiliser. Second, a narrow export base: the country earns foreign exchange mainly from a few crops, namely tobacco, tea and sugar, and if these fail to bring in enough foreign currency, the kwacha weakens further.
Third, limited buffers: because the economy is not diversified, its exports and industries are not spread across sectors, so one weak spot destabilises the whole system, and the country often lacks the reserves [foreign currency held by the central bank] or financial tools to cushion shocks. Fourth, household vulnerability: Malawians spend a large share of their income on food and energy, so when those prices rise, families feel the squeeze immediately, unlike in wealthier economies where essentials take up a smaller share of budgets.
In short, a weaker kwacha makes imports more expensive, and because Malawi depends so much on imports for everyday essentials, the impact flows straight into food and fuel prices, hitting households harder than in economies with broader production and stronger safety nets.
The Confluence: Your research looked at how Covid-19 changed the relationship between exchange rates and the money supply in Malawi. What did you find, and why would a pandemic change that relationship at all?
Dr. Banda: The study established that Covid-19 really did affect the structural relationship between exchange rates and the money supply, by making the kwacha appreciate, or gain value, against the US dollar. That appreciation could be attributed to the inflow of foreign currency into the country, in the form of foreign aid to help fight the pandemic.
The Confluence: You have also studied what makes firms listed on the Malawi Stock Exchange more or less profitable. What is one finding that surprised you, and what does it say about access to finance for businesses in Malawi generally?
Dr. Banda: The finding that surprised me a great deal was that liquidity, meaning how easily a firm can get hold of cash, has no effect on the profitability of firms listed on the Malawi Stock Exchange. One would expect liquidity to have a statistically significant [unlikely to be down to chance] effect on a firm's profitability, either positive or negative.
The positive influences can come through several channels. Operational efficiency: firms with strong liquidity can pay suppliers promptly, secure discounts and avoid disruptions, which supports smoother operations and higher margins. Investment opportunities: adequate liquidity lets firms seize growth opportunities without relying on expensive external financing. The cost of capital [what a firm pays to raise money]: strong liquidity reduces reliance on debt, lowering interest expenses and financial risk. And liquidity acts as a buffer against shocks such as currency volatility or supply-chain disruptions, preventing losses that erode profitability.
On the other hand, the negative effect of liquidity on a firm's profitability emanates from the fact that firms that prioritise excessive liquidity tend to sacrifice potential investment opportunities, thereby lowering their profitability.
The finding that liquidity has no influence on the profitability of firms in Malawi indicates that most Malawian firms do not have easy access to external finance. That, in turn, forces them to operate hand-to-mouth, limits their growth and increases their vulnerability to shocks.
The Confluence: Smallholder farmers make up a huge share of Malawi's economy. How does access to finance, or the lack of it, shape their ability to cope with swings in food and energy prices?
Dr. Banda: Access to finance gives smallholder farmers the ability to absorb shocks and invest in resilience. It enables them to buy inputs on time, to smooth their consumption [keep spending steady when income swings], and to invest in efficiency: for example, through loans or microfinance to fund irrigation, storage or solar energy, which reduces their dependence on volatile fuel and food markets.
It also works like insurance, helping farmers absorb sudden costs without falling into debt traps or selling off their livestock. Without access to finance, a smallholder can be forced into short-term survival strategies that undermine productivity and deepen their vulnerability to food and energy price swings.
The Confluence: If you had to explain to a room of teenagers why a country's GDP growth figure alone does not tell you much about whether ordinary people's lives are actually improving, what would you say?
Dr. Banda: GDP growth alone does not equal better lives, for four reasons. Distribution matters: if most of the growth comes from one sector, say big commercial farms or mining, ordinary families may not see any benefit. Prices matter: if food and fuel prices rise faster than incomes, people feel poorer even if GDP is growing. Jobs matter: growth that does not create decent jobs leaves young people stuck in poverty. And services matter: GDP does not measure whether schools, hospitals or roads are improving, nor does it measure environmental damage such as pollution.
The Confluence: What is one policy lever, whether a subsidy, an exchange-rate move or a lending programme, that you think could genuinely ease the squeeze between food prices, energy costs and access to finance for households right now?
Dr. Banda: One of the most powerful levers right now would be a targeted subsidy programme for fertiliser and fuel, because these two inputs sit right at the intersection of food prices, energy costs and household finance in Malawi. Fertiliser matters because without it, smallholder yields drop, food supply tightens and prices rise. Fuel matters because it drives transport costs, which ripple into food prices and household energy bills.
A well-designed fertiliser-and-fuel subsidy programme could ease this triple squeeze by lowering household costs, stabilising food supply and giving farmers the financial breathing room they need.
The Confluence: What first drew you to agricultural and financial economics rather than more mainstream macroeconomics?
Dr. Banda: In Malawi and many similar economies, agriculture is not just a sector: it is the backbone of daily life. When fertiliser prices spike or the rains fail, you do not just see GDP wobble, you see families struggling to eat. Studying agricultural economics means grappling with those very tangible connections between policy, markets and whether households can put food on the table. Agriculture is where economics meets survival.
Finance, meanwhile, is about resilience over a lifetime. Access to finance is the bridge between vulnerability and opportunity: a farmer with credit can buy inputs, withstand shocks and invest in productivity, while one without it is exposed to every swing in food and energy prices. Financial economics in this context is not abstract. It is about whether people can smooth their consumption, avoid distress sales [selling assets cheaply in an emergency] and climb out of poverty.
Mainstream macroeconomics looks at equally important issues, such as GDP growth, inflation or exchange rates in aggregate, but it can miss the lived reality of agriculture-based economies such as Malawi. Agricultural and financial economics put you closer to the ground, where economics is about survival, resilience and dignity, not just numbers.