Beyond the Bottom Line
Draws on the collapses of Enron and Carillion, both highly profitable on the surface until they weren't, to show how profit figures can be manipulated in ways cash flow can't.
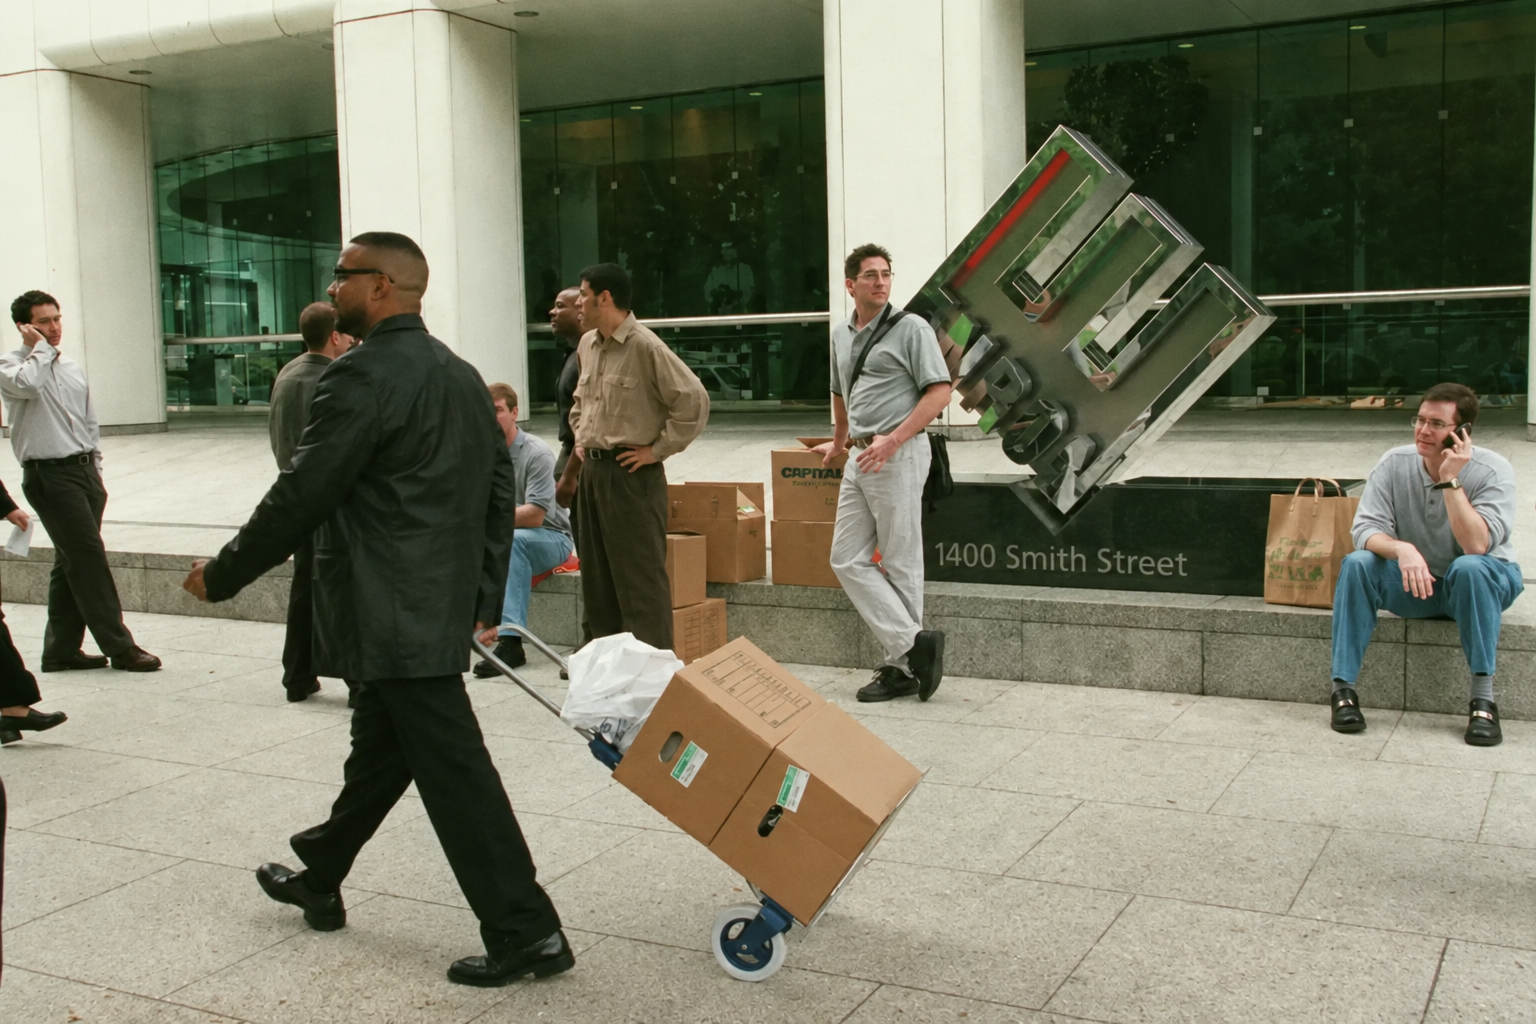
IN 2001, Enron was widely seen as one of the most successful companies in America. People trusted its growing profits, its share price went up continuously and analysts praised its growth. However, behind the strong financial results there were billions of dollars in hidden debt. Seventeen years later, Carillion appeared as a profitable and successful construction company, responsibly paying substantial dividends to its shareholders until suddenly collapsing with almost £7 billion in liabilities and only £29 million in cash. These failures make us wonder: if companies that appear to be profitable can still go bankrupt, how reliable is profit as a measure of success?
Profit is often used as the main indicator of business performance. Rising earnings attract investors, increase share prices, and generate positive headline images. However, profit numbers can be tricky as accounting methods affect how profits are reported. Profits do not necessarily reflect cash flow and often exclude factors which influence long-term success. Using the examples of Enron, Wirecard and Carillion, this piece examines how profit can be a deeply misleading measure of a company’s true financial health.
What Profit Measures
Profit is generally defined as the amount of money remaining after a company subtracts its costs from its revenue. This appears to be straightforward – if a company is earning more than it spends, it is profitable. However, accounting is more complex than measuring cash entering and leaving a business.
There are several forms of profit used in financial reporting. Gross profit measures revenue after production costs, operating profit reflects profits from business activities, and net profit represents the final earnings after taxes and interest payments. Investors often focus heavily on these figures because they appear to provide a reliable method for comparing businesses.
However, profit is largely based on accounting rules rather than physical cash. A company can recognise revenue before receiving payment, spread costs across years, or estimate future earnings based on projections. As a result, profit does not always represent the financial position of a company at a specific moment in time.
The difference becomes clearer when profit is compared with cash flow. Cash flow measures the movement of money into and out of a business. While profits may look strong on an income statement, poor cash flow can prevent a company from paying suppliers, employees, or debts. Many investors and analysts believe cash generation provides a more accurate measure of financial stability than profit alone.
Financial ratios help explain this issue. Liquidity ratios such as the current ratio and quick ratio check if a business can meet short term obligations, while operating cash flow ratios examine how effectively profits are converted into actual cash. These indicators are often more useful in assessing financial strength than profit figures alone.
How Companies Appear Profitable Without Being Healthy
One major weakness of profit as a measure of success is that accounting rules allow companies to choose how earnings are reported. While accounting standards aim to create consistency and transparency, they also involve estimates and judgement. In some cases, businesses can manipulate these rules to make profits look better on the surface and hide financial weaknesses.
The most famous example is Enron. Before its collapse in 2001, Enron was widely viewed as one of America’s most innovative companies. Investors admired its growth and its share prices increased dramatically throughout the 1990s. However, behind the profits the company was hiding billions of dollars of debt through complex off-balance-sheet entities.
Enron also used “mark-to-market” accounting, which allowed the company to record estimated profits immediately even when the cash had not yet been earned. This created an illusion of growth while masking serious financial problems. According to an analysis published by Forbes, Enron’s reported debt in 2000 was $10.2 billion while its actual debt was estimated to be over $22 billion. The company’s reported cash flow from operations also differed drastically from reality.
Eventually, confidence in the company collapsed, leading to bankruptcy and billions of dollars in shareholder losses. The scandal destroyed the accounting firm Arthur Andersen and contributed to the introduction of stricter financial regulations through the Sarbanes-Oxley Act in the US.
A more recent example is Wirecard, a German financial technology company once regarded as one of Europe’s leading fintech firms. In 2020 the company admitted that €1.9 billion supposedly held in bank accounts probably did not exist. Investors had trusted the company’s reported profits and rapid growth, yet the accounts had been manipulated for years. The scandal demonstrated that even modern financial markets can struggle to identify accounting fraud.
These cases reveal a fundamental limitation of profit figures. Financial statements are not purely objective measurements – they depend heavily on assumptions, estimates, and transparency. When these elements fail, reported profits can become highly misleading.
Why Cash Flow Often Matters More
Although profitability attracts attention, cash flow frequently provides a more realistic picture of financial health. A company cannot pay wages, suppliers, or debts using accounting profits alone. It requires cash.
The collapse of Carillion demonstrates this clearly. Before entering liquidation in January 2018, Carillion was one of the United Kingdom’s largest construction and outsourcing companies. It managed public infrastructure projects and employed tens of thousands of workers. Despite appearing profitable for years, the company suffered serious cash flow problems and accumulated massive debt.
Parliamentary reports later revealed that Carillion’s liabilities approached £7 billion while the company held just £29 million in cash at the time of collapse. Remarkably, the business continued paying dividends to shareholders even as its finances deteriorated.
Analysts also criticised Carillion’s accounting practices. The company often recognised profits on long-term contracts before cash had actually been received. According to the House of Commons Library, Carillion’s profits increasingly diverged from the cash generated by its operations.
This difference between accounting profit and cash generation became one of the most telling warning signs of the company’s underlying weakness. While official profit figures suggested stability, poor liquidity and rising debt created an increasingly precarious financial position.
Carillion’s collapse highlights why many investors pay close attention to measures such as free cash flow, debt-to-equity ratios and operating cash flow. These indicators provide insight into whether profits are supported by genuine financial strength rather than accounting assumptions.
Long-term Success Versus Short-term Profit
Another reason profit does not always indicate success is that businesses sometimes prioritise short-term earnings at the expense of long-term stability. Public companies are often under pressure to satisfy shareholders by meeting profit expectations. As a result, executives may focus excessively on short term financial performance.
This can encourage dangerous behaviour. Companies may reduce investment in research, delay essential spending, or take on excessive debt to improve short-term profits. While these strategies can temporarily increase earnings, they often weaken the business over time.
The global financial crisis of 2008 provides a striking example. Major institutions – among them Lehman Brothers, whose collapse in September 2008 triggered the worst financial crisis since the Great Depression – generated profits by issuing increasingly risky mortgage backed loans and investing heavily in complex financial products built on them. In the short term, profits appeared strong, encouraging further risk-taking.
However, these profits depended on increasingly fragile foundations: the assumption that housing prices would rise indefinitely. When housing markets weakened and borrowers began defaulting, the profits evaporated and the losses were catastrophic – Lehman Brothers alone reported $3.9 billion in losses in its final quarter.
This demonstrates that profitability without sustainability can create a dangerous false sense of security. Strong businesses require not only profits, but also responsible risk management, stable cash generation, and long-term planning.
Modern investors increasingly recognise this distinction. Rather than focusing exclusively on earnings, analysts now evaluate multiple financial indicators, including leverage ratios, liquidity measures, and future growth potential. This broader approach reflects the understanding that financial success is more complex than a single profit figure.
The Limitations of Profit
Although profit is one of the most important indicators in accounting, no single metric can fully measure business success. Profit ignores factors that contribute to long-term performance, including innovation, customer loyalty, operational efficiency, and market reputation.
A business may temporarily increase profits by cutting investment in technology or employee development, for example, while damaging its long-term competitiveness. Similarly, accounting figures cannot fully capture the value of trust and reputation – both of which can disappear rapidly after scandals.
Financial statements therefore require interpretation rather than blind acceptance. Investors, regulators, and analysts increasingly rely on a combination of measures and financial ratios to assess companies more accurately. Metrics such as return on equity, free cash flow, liquidity ratios, and debt levels often provide better insight into financial health than profit alone.
The failures of Enron and Carillion demonstrate that relying exclusively on profitability can be catastrophic. In both cases, reported earnings masked structural weaknesses that eventually became impossible to hide.
Conclusion
Enron’s accounts looked immaculate until the morning they didn’t. Carillion paid dividends while haemorrhaging cash. Wirecard’s billion euro hole had been there for years before anyone found it. Profit, it turns out, is an opinion. Cash is a fact.
Cash flow, debt levels, and liquidity ratios often tell a truer story than the headline profit figure. And beyond the financials, the factors that determine whether a business survives in the long run – innovation, reputation, customer trust – do not appear on any income statement. A profitable company is not necessarily a healthy one. The difference matters enormously, and the consequences of ignoring it can be catastrophic.